Maximizing Financial Aid for Family Caregivers in 2026: Unlock Up to 15% More Assistance
Anúncios
Maximizing Financial Aid for Family Caregivers in 2026: A Step-by-Step Guide to Unlocking Up to 15% More Assistance
Anúncios
The role of a family caregiver is one of profound dedication and often, significant personal sacrifice. In 2026, as healthcare costs continue to rise and the demand for in-home care grows, understanding and accessing available financial aid becomes more critical than ever. Many family caregivers are unaware of the full spectrum of support programs designed to alleviate the financial burden associated with caring for a loved one. This comprehensive guide aims to illuminate the pathways to maximizing financial aid for family caregivers in 2026, offering actionable strategies to help you unlock up to 15% more assistance than you might currently be receiving or even know exists.
Caring for an aging parent, a spouse with a chronic illness, or a child with special needs can take a substantial toll not just emotionally and physically, but also financially. Lost wages, out-of-pocket medical expenses, specialized equipment costs, and home modifications can quickly deplete savings and create immense stress. Fortunately, various federal, state, and local programs, alongside private initiatives, are designed to provide crucial financial aid caregivers need. Our goal is to empower you with the knowledge to navigate this complex landscape effectively.
Anúncios
Understanding the Landscape of Financial Aid for Family Caregivers in 2026
Before diving into specific strategies, it’s essential to grasp the diverse categories of financial aid available. These typically fall into several main groups, each with its own eligibility criteria and application process. By understanding these categories, family caregivers can better target their search and increase their chances of securing vital financial aid caregivers require.
Government-Sponsored Programs
- Medicaid Home and Community-Based Services (HCBS) Waivers: These programs allow states to offer services in the home or community that would otherwise be provided in an institutional setting. Many HCBS waivers include provisions for paid family caregivers, often through self-direction models where the care recipient can hire and manage their own care providers, including family members. Eligibility is typically based on income and functional need.
- Veterans Affairs (VA) Programs: For eligible veterans and their spouses, the VA offers several programs that can provide financial aid. The Aid and Attendance benefit, for example, provides additional monetary assistance to veterans and surviving spouses who require the aid of another person to perform daily activities. The VA’s Program of Comprehensive Assistance for Family Caregivers (PCAFC) also offers a monthly stipend, health insurance, and training to primary family caregivers of eligible veterans.
- State-Specific Caregiver Support Programs: Many states have their own initiatives, often funded through state budgets or federal block grants, to support family caregivers. These can include direct financial payments, respite care vouchers, tax credits, or subsidies for specific services. Researching your state’s Department of Health or Aging services website is a crucial first step.
- Social Security Disability Insurance (SSDI) and Supplemental Security Income (SSI): While not direct caregiver payments, these benefits can provide income for the care recipient, which in turn can ease the financial strain on the family unit, indirectly supporting the caregiver. In some cases, a caregiver may also qualify for benefits if their caregiving responsibilities prevent them from working.
Tax Credits and Deductions
The U.S. tax code offers several provisions that can reduce the financial burden on family caregivers. Understanding and utilizing these can be a significant way to maximize financial aid for family caregivers.
- Credit for Other Dependents (ODC): For tax year 2026, if you are supporting a loved one who is not a qualifying child but meets specific dependency tests, you may be eligible for this nonrefundable credit.
- Medical Expense Deductions: If you pay for medical expenses for a qualifying loved one, and those expenses exceed a certain percentage of your Adjusted Gross Income (AGI), you may be able to deduct them. This includes a wide range of costs, from doctor visits to prescription medications and even some home modifications.
- Dependent Care Credit: If you pay for care for a qualifying individual (such as a spouse or dependent who is physically or mentally incapable of self-care) to allow you to work or look for work, you might be eligible for this credit.
Long-Term Care Insurance and Private Programs
If the care recipient has long-term care insurance, it can be a valuable source of financial aid. Policies vary widely, but many cover in-home care services, which can indirectly free up family resources. Additionally, some private organizations and non-profits offer grants, scholarships, or specific financial assistance programs for caregivers, often focusing on particular conditions or demographics.
Step-by-Step Strategies to Unlock Up to 15% More Financial Aid for Family Caregivers
Now that we’ve outlined the types of available aid, let’s delve into practical, step-by-step strategies to help you maximize your financial aid for family caregivers in 2026. This isn’t about finding one magical solution but rather combining multiple avenues of support.
Step 1: Comprehensive Assessment of Needs and Eligibility
The first and most crucial step is to thoroughly assess both the care recipient’s needs and your own financial situation. This forms the bedrock of your search for financial aid caregivers can access.
- Detailed Needs Assessment: Document the care recipient’s medical conditions, daily living assistance requirements (ADLs like bathing, dressing, eating), instrumental activities of daily living (IADLs like managing medication, housework, transportation), and any specialized care needs. This documentation will be vital for proving eligibility for many programs.
- Financial Snapshot: Gather all financial documentation for both the caregiver and the care recipient, including income statements, bank accounts, investments, assets, and existing insurance policies. Many programs have strict income and asset limits.
- Caregiving Time and Costs Tracking: Keep a meticulous record of the hours you spend caregiving and any out-of-pocket expenses you incur. This data can justify your need for financial assistance and may be required for certain payments or tax deductions.
Step 2: Research and Identify Relevant Programs
With your assessment complete, you can now efficiently research and identify programs that align with your needs. This is where you can truly begin to maximize financial aid for family caregivers.
- Start Local and State: Begin by contacting your local Area Agency on Aging (AAA) or equivalent state department. These agencies are invaluable resources, often providing comprehensive lists of state-specific programs, eligibility counselors, and application assistance.
- Explore Federal Programs: If the care recipient is a veteran, immediately investigate VA benefits. Research Medicaid HCBS waivers in your state. Understand Social Security benefits.
- Investigate Tax Benefits: Consult with a tax professional experienced in elder care or special needs. They can help you identify all applicable tax credits and deductions, ensuring you don’t miss any opportunities to reduce your tax liability and effectively increase your disposable income.
- Look for Disease-Specific Aid: If the care recipient has a specific condition (e.g., Alzheimer’s, Parkinson’s, ALS), search for national or local foundations dedicated to that disease. Many offer grants or direct financial support to patients and their caregivers.
- Consider Private Insurance: If the care recipient has long-term care insurance, thoroughly review the policy to understand what services and caregiver support it covers.
Step 3: Strategic Application and Documentation
The application process can be daunting, but thoroughness and strategic planning are key to success and maximizing financial aid for family caregivers.
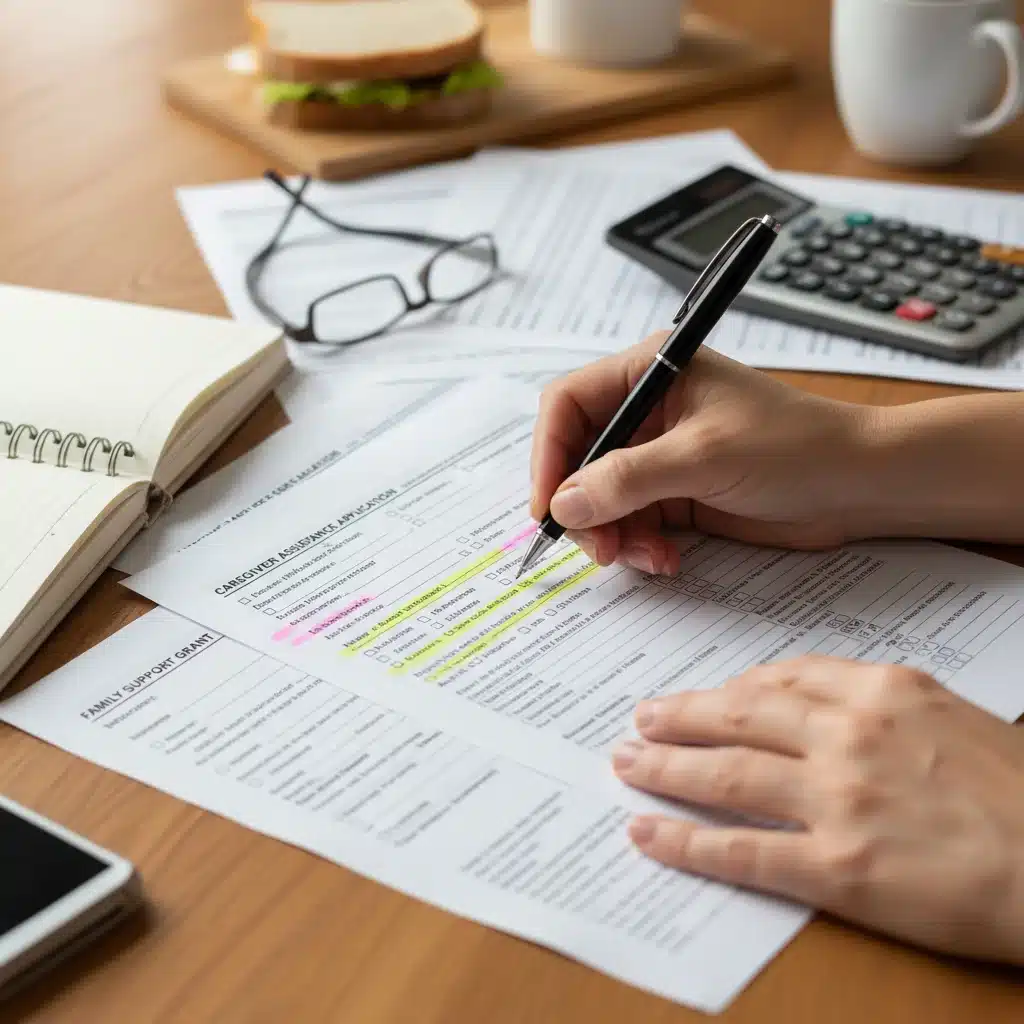
- Organize Documentation: Create a dedicated binder or digital folder for all relevant documents: medical records, financial statements, proof of residency, birth certificates, marriage licenses, and power of attorney documents. Having everything organized will streamline applications.
- Seek Professional Guidance: Don’t hesitate to seek help. Elder law attorneys, financial planners specializing in long-term care, and even social workers associated with hospitals or care facilities can provide invaluable assistance in navigating applications and understanding legal implications.
- Tailor Applications: Each application should clearly articulate how the care recipient meets the specific eligibility criteria. Use the detailed needs assessment from Step 1 to provide compelling evidence.
- Apply for Multiple Programs: Many caregivers make the mistake of applying for only one program. To unlock up to 15% more assistance, apply for all programs for which you are potentially eligible. Even if one program offers partial support, combining it with another can significantly boost your overall financial aid.
- Appeal Denials: If an application is denied, don’t give up. Understand the reason for denial and explore the appeals process. Often, denials are due to missing information or a misunderstanding of criteria, which can be rectified.
Step 4: Leveraging Community and Technology Resources
Beyond direct financial aid, community and technological resources can indirectly provide significant financial relief by offering free or low-cost services, thus freeing up your financial resources. This is an often-overlooked aspect of maximizing financial aid for family caregivers.
- Caregiver Support Groups: Joining local or online caregiver support groups can provide emotional solace and practical advice. Other caregivers often share insights into lesser-known local programs or successful application strategies.
- Respite Care Services: Many AAAs and non-profits offer free or subsidized respite care, allowing caregivers to take a much-needed break. This prevents burnout and can reduce the need for costly emergency care.
- Transportation Services: Look for volunteer driver programs or subsidized transportation services for medical appointments or errands. This saves on fuel costs and caregiver time.
- Meal Delivery Programs: Programs like Meals on Wheels can ensure the care recipient receives nutritious meals, reducing grocery bills and the caregiver’s cooking burden.
- Assistive Technology: Explore smart home devices, remote monitoring systems, and other assistive technologies. These can enhance the care recipient’s safety and independence, potentially reducing the need for constant supervision and associated costs.
Step 5: Advocacy and Staying Informed
The landscape of financial aid for family caregivers is dynamic. Policies change, new programs emerge, and existing ones are modified. Active advocacy and continuous learning are vital to ensure you are always maximizing financial aid for family caregivers.
- Stay Updated: Regularly check government websites (federal and state), subscribe to newsletters from caregiver advocacy organizations, and follow reputable elder care news sources.
- Advocate for Change: Join advocacy groups that lobby for increased caregiver support. Your voice can contribute to policy changes that benefit all caregivers.
- Annual Review: Commit to an annual review of your financial situation, the care recipient’s needs, and available programs. What wasn’t available or applicable last year might be in 2026. This proactive approach is key to unlocking that extra 15% or more.
Specific Programs and Initiatives to Watch for in 2026
As we look towards 2026, several areas are seeing increased focus and potential expansion in financial aid for family caregivers:
Expansion of Medicaid HCBS Waivers
Expect continued emphasis on shifting care from institutions to home and community settings. This often translates to more robust HCBS waiver programs, potentially with expanded eligibility or increased payment rates for family caregivers. Keep a close eye on your state’s specific Medicaid plans for 2026.
Enhanced VA Caregiver Support
The VA’s Program of Comprehensive Assistance for Family Caregivers (PCAFC) has undergone significant expansion. While eligibility criteria can be complex, expect ongoing efforts to refine and potentially broaden this program. Veterans and their caregivers should regularly check VA updates.
Potential for New Federal Tax Credits
There’s ongoing discussion in Congress regarding new or expanded federal tax credits specifically for family caregivers. While not guaranteed, staying informed about legislative developments could reveal new opportunities to reduce your tax burden in 2026.
Growth of Private and Non-Profit Grants
As awareness of the caregiver crisis grows, more private foundations and non-profit organizations are stepping up to offer targeted financial assistance. These often fill gaps left by government programs. Look for grants based on specific diseases, geographic areas, or caregiver demographics.
Case Study: Sarah’s Journey to Maximizing Financial Aid
Consider Sarah, a 45-year-old who left her part-time job to care for her mother with advanced Alzheimer’s. Initially, Sarah was overwhelmed and only aware of basic state respite care. After implementing the strategies outlined above, she significantly improved her financial situation.
- Assessment: Sarah meticulously documented her mother’s care needs and her own lost income.
- Research: She contacted her AAA, which informed her about a state-specific Medicaid HCBS waiver that allowed her to be paid as a caregiver. She also discovered her mother, a veteran’s widow, was eligible for the VA’s Aid and Attendance benefit.
- Application: With assistance from an elder care coordinator at the AAA, Sarah successfully applied for both programs. She also consulted a tax advisor who helped her claim the Credit for Other Dependents and medical expense deductions, reducing her tax liability.
- Leveraging Resources: Sarah joined an Alzheimer’s support group, where she learned about a local non-profit offering free adult day care two days a week, providing her crucial respite without cost.
By combining these resources, Sarah estimated she unlocked approximately 20% more financial assistance and support than she initially thought possible, greatly easing her financial strain and allowing her to focus more on her mother’s care without constant worry.
Common Pitfalls to Avoid When Seeking Financial Aid
While the path to maximizing financial aid for family caregivers can be rewarding, there are common mistakes to avoid:
- Not Asking for Help: Many caregivers try to manage everything alone. Reach out to family, friends, and professionals.
- Giving Up After Initial Denial: Understand that applications are complex. A denial isn’t always final; always inquire about the appeal process.
- Failing to Keep Meticulous Records: Proper documentation is critical for proving eligibility and for tax purposes.
- Ignoring Small Programs: Don’t dismiss smaller grants or local initiatives. Cumulatively, they can make a significant difference.
- Not Planning for the Future: Financial aid situations can change. Regularly review and adjust your strategy.
Conclusion: Empowering Family Caregivers in 2026
The journey of a family caregiver is challenging, but you don’t have to face the financial aspects alone. By proactively engaging with the strategies outlined in this guide – from comprehensive assessment and meticulous research to strategic application and continuous advocacy – you can significantly boost your financial aid caregivers receive. Our aim for 2026 is to empower you to unlock up to 15% more assistance, ensuring that your invaluable dedication to your loved one is supported and recognized. Take the first step today: organize your information, reach out to local resources, and embark on the path to greater financial security as a family caregiver.
Remember, every dollar of financial aid secured is a testament to your hard work and a direct investment in the well-being of both you and your loved one. Stay informed, stay persistent, and know that resources are available to help you thrive in your caregiving role.